Why are LEVIA sticks reported under the e-cigarette liquids category?
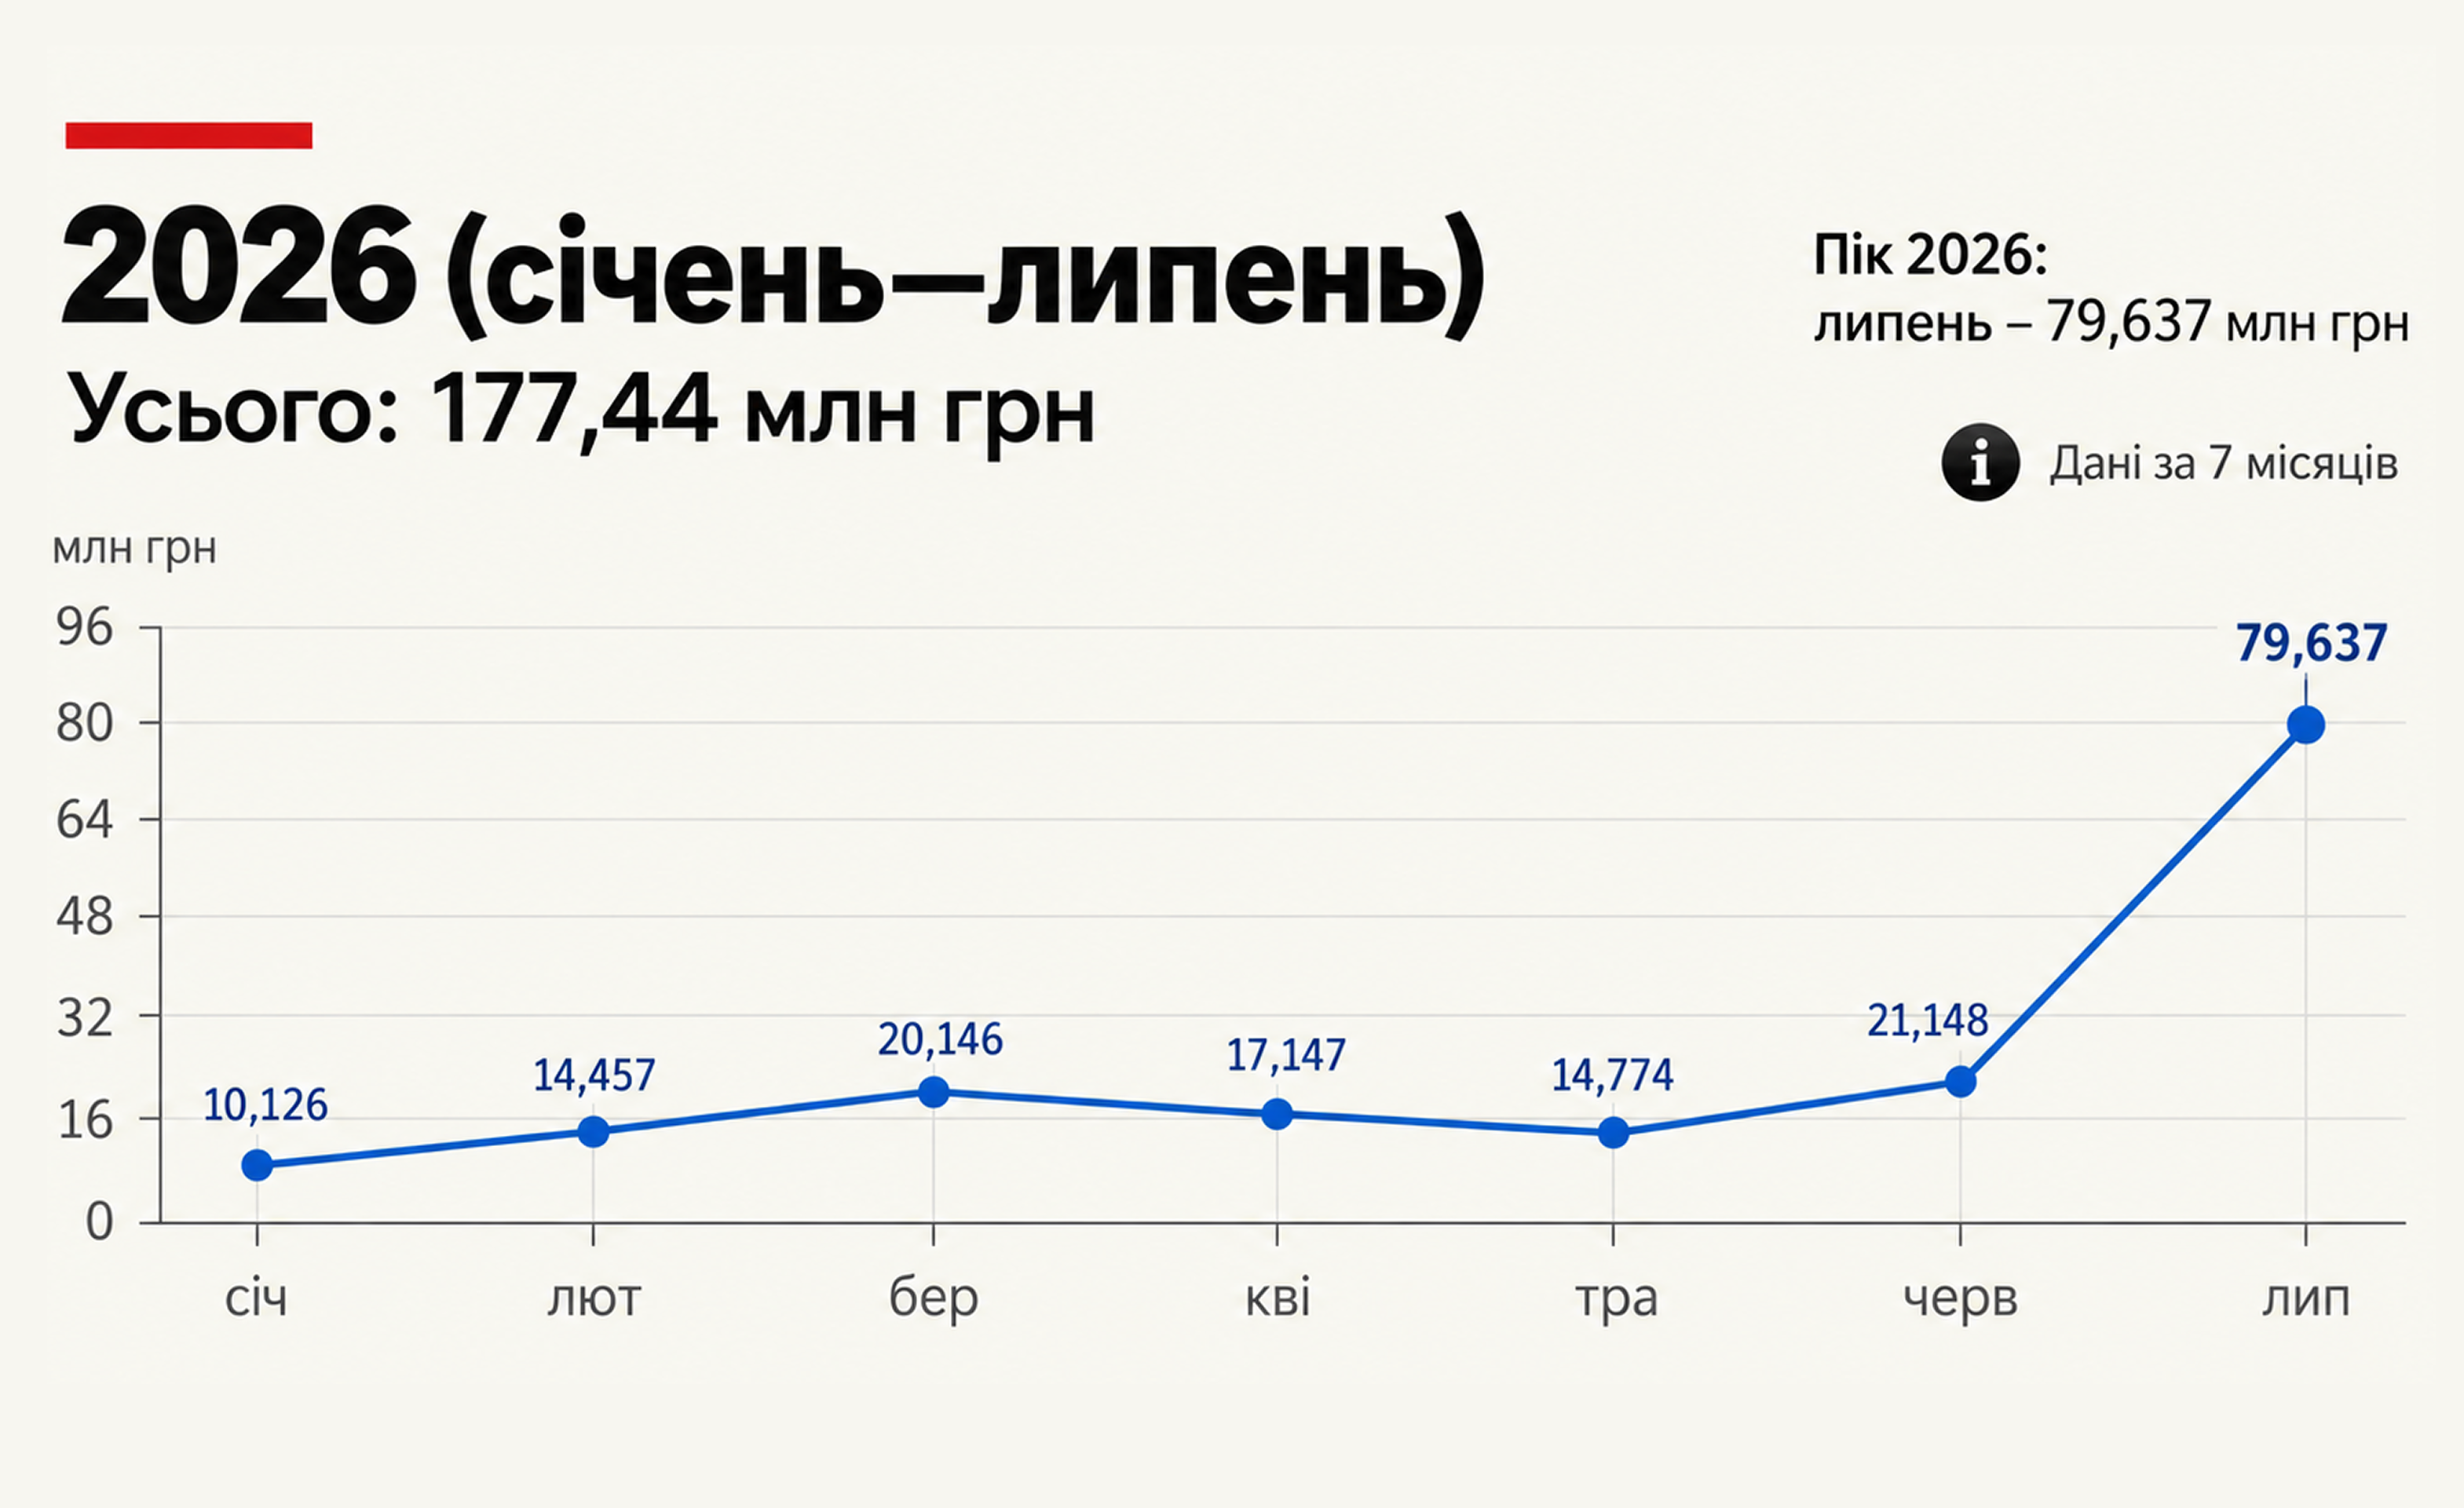
In July, total tax revenues increased from UAH 21.1 million to UAH 79.6 million — more than tripling.
However, excise tax revenues from liquids produced in Ukraine declined over the same period: from UAH 14.94 million in June to UAH 11.34 million in July — a decrease of 24%.
The bulk of the increase in July came from imports: UAH 57.81 million in excise tax revenues, accounting for more than 72% of the total. These revenues are associated with imports of LEVIA — tobacco-free nicotine-containing sticks designed for heating.
LEVIA products are tobacco-free nicotine-containing sticks that are structurally different from the liquids used in electronic cigarettes.
In these sticks, the nicotine-containing liquid is incorporated into a solid insert made from cellulose fibres rather than being present as a liquid mixture. At the same time, under the Tax Code, products classified under Ukrainian Classification of Goods for Foreign Economic Activity (UKT ZED) code 2404 12 00 90 fall within the excise category of “liquids used in electronic cigarettes”, subject to an excise duty rate of EUR 300 per litre. Yet the Code itself defines such liquids as liquid mixtures used to generate vapour in electronic cigarettes.
This raises an issue concerning legislative classification and official statistics. Products that differ in both their design and method of use are being included in the same excise category.
As a result, significant imports of nicotine-containing sticks may appear in official statistics as a sharp increase in revenues from the market for liquids used in electronic cigarettes — even when revenues from domestically produced liquids are declining. This makes it difficult to assess the actual market dynamics: the headline figure of UAH 79.6 million does not indicate whether the legal e-liquid segment is expanding or whether the increase is driven by the introduction of a different type of product.
For an accurate assessment of market dynamics, tax revenues from e-cigarette liquids, tobacco-free sticks and other nicotine-containing products should be reported separately. Such an approach would make it possible to track the actual performance of each market segment and determine which specific product categories are driving changes in excise tax revenues.